
Can Bonds Still Diversify Multi-Asset Portfolios? Income versus Duration in Distinct Correlation Regimes
Analyzing Income, Duration, and Correlation in Multi-Asset Investing
Who will you meet?
About the Masterclass
We analyze the diversification benefits of fixed-income instruments under time-varying correlations. We estimate monthly, non-overlapping correlations from daily 10-year Treasury bond returns over the period January 1962 to May 2025. With these data, we use a hidden Markov model to identify three distinct correlation regimes, negative, zero, and positive. These regimes are highly persistent and differ in their diversification value depending on the importance of income versus duration as drivers of bond returns. Dynamically altering the mix of multi-asset portfolio allocations based on the most likely correlation regime materially improves returns while controlling risk.
What will you learn?
Discover data-driven portfolio strategies
Learn hidden Markov model applications
Understand bond diversification dynamics
Exclusive Benefits
Career Insights and Opportunities
Learn about the Berkeley HAAS experience
Networking and Access to Expert Insights
University of California, Berkeley | Haas School of Business (MFE)
A globally-recognised institution committed to academic excellence, innovation, and producing leaders who shape industries and societies. Through rigorous coursework, world-class faculty, and a vibrant community of scholars from across the world, students gain the knowledge, networks, and confidence to thrive in their chosen careers.
Your Pathway to a Top University Starts Here
Join the masterclass — it's free and takes less than 30 seconds to register.
Quick Signup
Trusted by Students
Frequently Asked Questions
Get all your questions answered about SEED Masterclasses!
Contact us
For any queries, please feel free to reach out to us!
Suggested Masterclasses
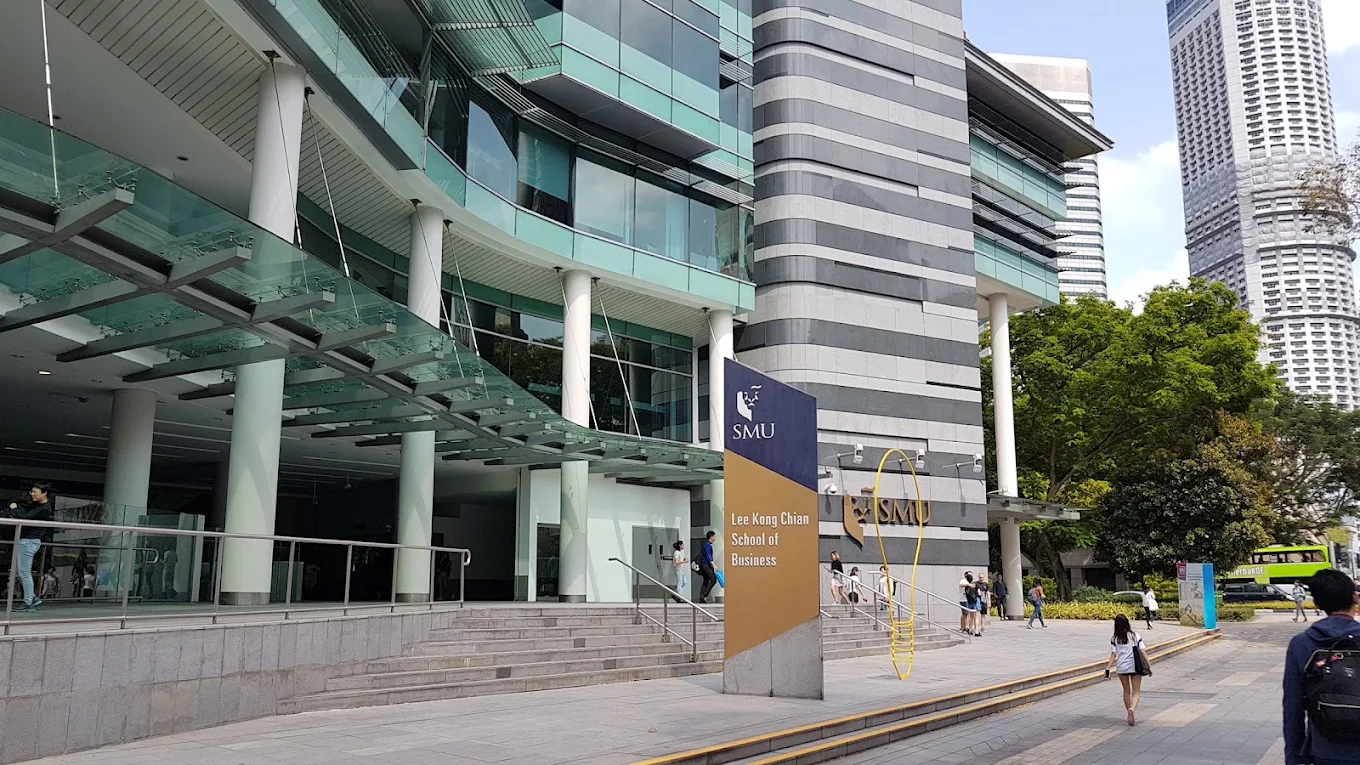
Study in Singapore, Build for the World: Singapore Management University
19 November 2026
7:30 AM EDT

Cracking the Analytics Code: Minnesota Carlson's Guide to Success in the USA!
17 November 2026
9:30 AM EDT